What happened?
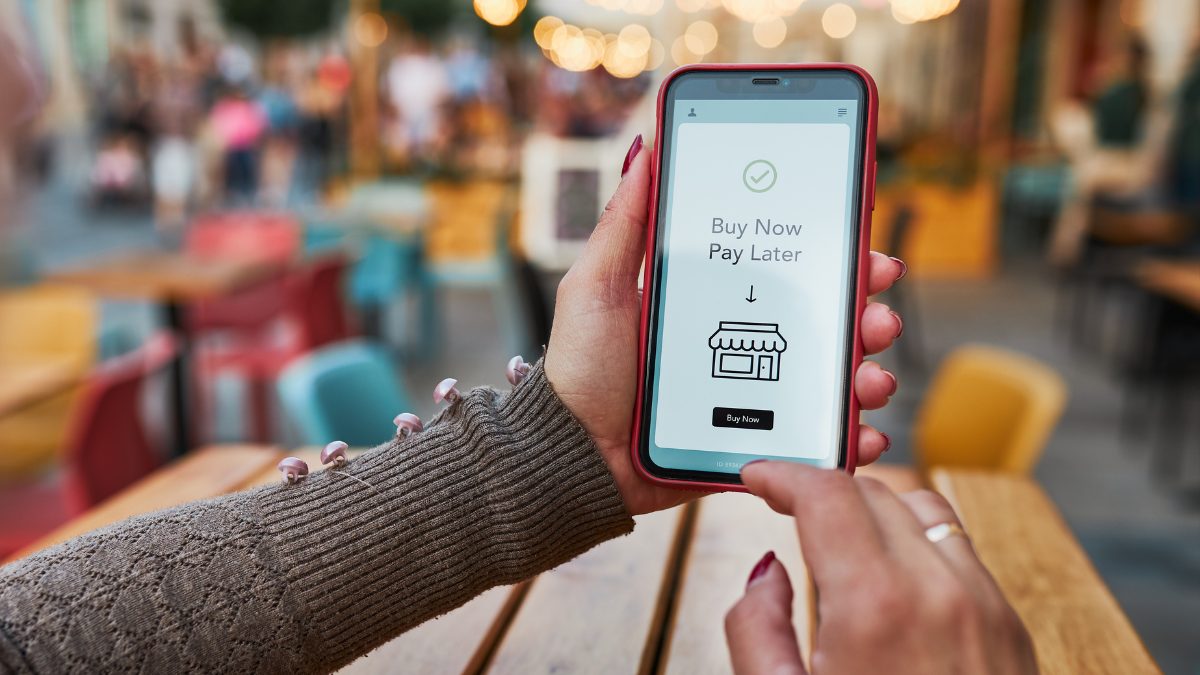
From 15 July, buy now, pay later providers fall fully within the UK regulatory perimeter, bringing affordability checks, clearer disclosures and Consumer Duty obligations into focus.
In Ruth Prickett’s piece for Compliance Week, TCC Group CEO Joe Norburn explains why this shift was always likely, given the rapid growth of frictionless borrowing outside full regulation.
Why does it matter?
Joe Norburn argues that stronger oversight should help address the risks created by frictionless borrowing, particularly for customers with lower financial resilience who may be more exposed to unaffordable borrowing.
The change signals that BNPL can no longer be treated as a lightly supervised alternative to mainstream credit, and firms should expect the same scrutiny applied to other regulated lending.
Supporting sources
Frequently asked questions
When did BNPL come under full UK regulation?
BNPL providers fell fully within the UK regulatory perimeter from 15 July, bringing affordability checks, clearer disclosures and Consumer Duty obligations into scope.
Why does TCC's CEO see this as positive?
Joe Norburn believes stronger oversight should help address the risks created by frictionless borrowing, particularly for customers with lower financial resilience.
- Are your suitability reviews providing insight or just oversight?Analysis & Perspectives · September 24, 2026
- European Business Magazine: Why firms are turning to on-demand financial crime expertiseAnalysis & Perspectives · September 23, 2026
- What the FCA’s expanded AML role signals for firmsRegulatory Horizon · September 23, 2026
- Are your funds ready for the FCA’s new liquidity rules?Analysis & Perspectives · September 23, 2026
- Lending & Consumer CreditTCC helps consumer credit firms evidence good outcomes, strengthen affordability and vulnerability frameworks, and manage complaints, remediation and regulatory risk. We support lenders with practical, regulator-ready compliance programmes that improve governance, customer treatment and operational resilience.
- Payments & FinTechTCC helps payment institutions, e-money firms, FinTechs, challenger businesses and regulated technology providers strengthen compliance, manage regulatory change and demonstrate effective customer outcomes. From financial crime controls and APP fraud prevention to operational resilience, safeguarding and Consumer Duty governance, we help firms build regulator-ready frameworks that support growth without compromising control. For more than 25 years, TCC has helped FCA-regulated firms navigate evolving regulatory expectations with confidence.
Reviewed by TCC Group Editorial Team